
September 15, 2026
Louis C. Bernardi, “The Benefits Whisperer”
The Healthcare Heist Newsletter – by Lou Bernardi, The Benefits Whisperer, Certified Healthcare Fiduciary Coach, Certified Health Value Advisor.
_________________________________________________________________________
But Everyone at the Table Has to Think Differently
Let’s start with something I think almost everyone can agree on.
There is something wrong with healthcare and health insurance in America.
CEOs know it. CFOs know it. HR leaders know it. Benefit advisors know it.
And employees certainly know it.
We spend more. Premiums go up. Deductibles get larger. Prescription drugs become more expensive. Employees struggle to navigate the system.
Yet every fourth quarter, we turn back to essentially the same system and ask it to rescue us.
Maybe that’s the first thing that needs to change.
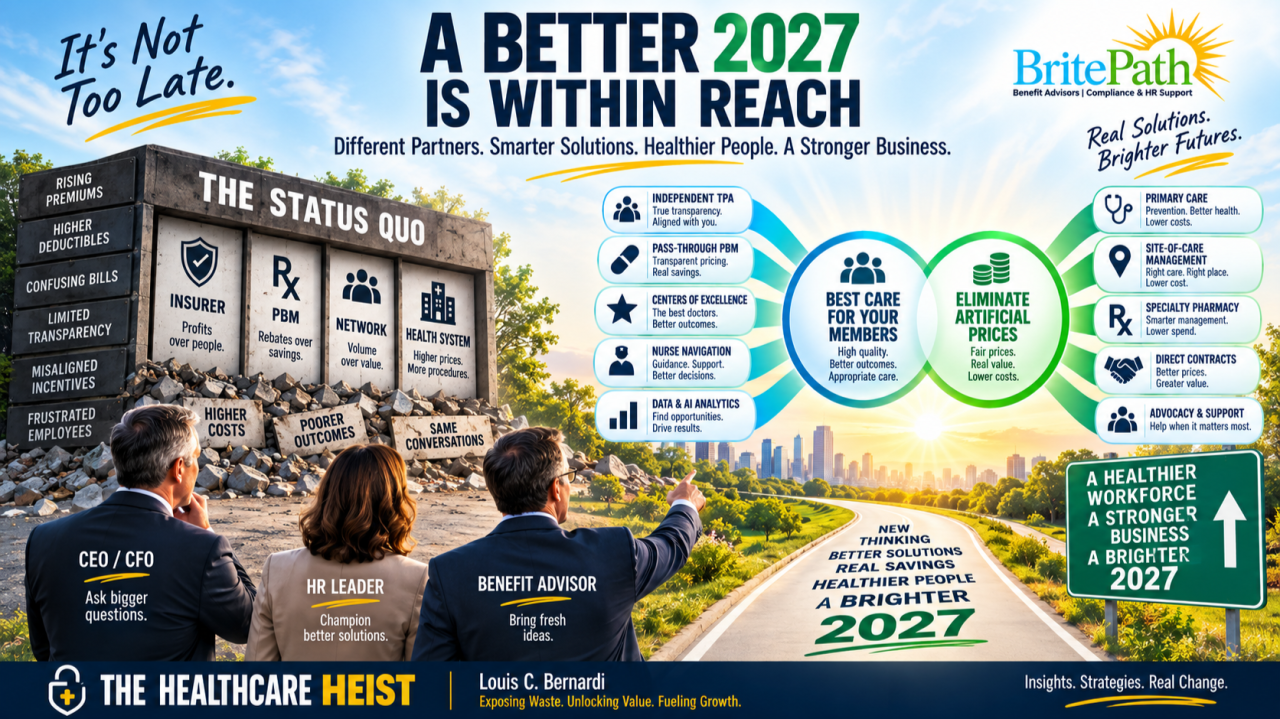
DON’T EXPECT THE STATUS QUO TO FIX THE STATUS QUO
If you want better results in 2027, the answer probably isn’t going to magically appear inside your renewal.
It may require bringing new thinking and new solution partners to the table.
Some can work inside your existing health plan. Others can supplement it from the outside. And for employers ready to go further, some can replace pieces of the traditional bundled model entirely.
Independent pharmacy solutions. Centers of Excellence. Direct contracts. Healthcare navigation. Second opinions. Primary care strategies. Site-of-care management. Independent TPAs. Alternative networks. Transparent pricing.
These aren’t simply “benefits.”
They are tools that can work together toward two incredibly important objectives:
1. Get members to the right doctors and facilities.
Not simply the closest provider or someone who happens to be in-network.
We should be helping members find high-quality care based on outcomes, experience and appropriateness of care.
2. Eliminate artificial healthcare prices.
We should be questioning what the plan is actually paying for hospitals, procedures, medications and other services—and whether those prices represent reasonable value.
Do those two things well and something interesting happens.
You don’t have to choose between taking care of employees and controlling costs.
Better care can cost less.
THE BIGGEST MISCONCEPTION ABOUT HEALTH INSURANCE
Here’s one of the most important concepts I wish every plan sponsor understood:
A negotiated discount does not necessarily mean you’re getting a good price.
For years, employers have been conditioned to believe that the enormous purchasing power of a major insurance company meant the insurer would negotiate favorable healthcare prices on their behalf.
Sometimes it does.
But increasingly available healthcare pricing data has allowed employers and advisors to look beyond the word “discount” and examine the actual price being paid.
And that can tell a very different story.
Think about it this way:
If a hospital establishes a price of $100,000 and your insurer negotiates it down to $50,000, you’ve received a 50% discount.
Sounds fantastic.
But what if another purchaser can obtain that same high-quality procedure for $25,000?
Suddenly, that 50% discount doesn’t look nearly as impressive.
The discount isn’t what matters. The final price is.
And neither price nor network status tells us whether the member is being directed to the provider most likely to deliver the appropriate care and a great outcome.
That’s why today’s plan sponsor needs to understand more than premiums, deductibles and copays.
THIS REQUIRES THREE MINDSET SHIFTS
Benefit advisors need to think differently.
Your value can’t simply be negotiating the renewal and presenting alternative insurance plans.
Bring solutions.
Show clients what’s driving their claims. Question prices. Examine pharmacy. Identify high-cost categories. Bring independent partners to the table when they can outperform the status quo.
And perhaps most importantly, be willing to recommend something that isn’t already sitting on the carrier’s shelf.
HR leaders need to think differently.
Change doesn’t automatically mean disruption.
Done correctly, changing how employees access healthcare can mean better navigation, better doctors, fewer unnecessary procedures, lower out-of-pocket costs and someone actually helping the member when healthcare gets complicated.
That’s not reducing benefits.
That’s improving them.
CEOs and CFOs need to think differently.
Stop treating healthcare as an insurance decision delegated almost entirely to HR once a year.
For many organizations, healthcare is one of their largest expenses outside payroll.
Treat it accordingly.
Understand the fundamentals. Ask where the money goes. Ask what you’re paying for healthcare. Ask what you’re paying for medications. Ask whether your incentives are aligned with the organizations managing those dollars.
You don’t need to become a healthcare expert.
But you need to know enough to ask better questions.
MAYBE WE WERE FOOLED
This may be the hardest mindset shift.
Plan sponsors have trusted the system for decades.
We trusted that bigger networks meant better access.
We trusted that negotiated discounts meant better prices.
We trusted that rebates meant lower pharmacy costs.
We trusted that the organizations managing billions of healthcare dollars were financially aligned with the employers and employees paying the bills.
Maybe some of those assumptions deserve another look.
There’s no shame in saying:
“We didn’t know what we didn’t know.”
The mistake would be having access to better information today and continuing to make decisions as if we didn’t.
IT’S NOT TOO LATE FOR 2027
We’re approaching the official start of fourth-quarter renewal season.
Your renewal may already be coming.
Maybe it’s already sitting on your desk.
That doesn’t mean your 2027 strategy has been decided.
You don’t necessarily have to blow up your health plan on January 1.
Start somewhere.
Introduce one solution.
Investigate one major cost driver.
Analyze your pharmacy arrangement.
Question one hospital price.
Explore one independent partner.
Give members a better way to find high-quality care.
And start building the health plan you actually want rather than simply renewing the one you already have.
Because the solution to America’s healthcare problem isn’t likely to arrive neatly packaged inside your renewal envelope.
It will come from employers, advisors and solution partners willing to think differently—and work together to build something better.
So before you sign your 2027 renewal, get your advisor, HR leader and CEO/CFO around the same table and ask one question:
“If we were building our health plan from scratch today, knowing what we know now, would we build the plan we currently have?”
If the answer is no, don’t be discouraged.
Be excited.
Because it’s not too late to change your 2027 healthcare story.
But this time, you’re going to have to write it yourself.
Already Have Your 2027 Renewal?
Before you sign it, make sure you get the opportunity to look at it through a different lens.
Not just premiums and deductibles. Healthcare prices. Pharmacy costs. Quality. Claims. Incentives. And the solutions you may not have been shown.
You may decide your current plan is exactly where you should be.
Or you may discover an opportunity you didn’t know existed.
Either way, you’ll know more than you did before.
→ Getting a Second Opinion Before You Renew is always Prudent
Contact the author at lcbernardi@britepathbenefits.com
Schedule a call at calendly.com/lcbernardi
Visit our website at www.britepathbenefits.com